If you own or operate a small vending machine business, you already know that one unexpected equipment failure or a liability claim can wipe out months of profit. Unlike large operators with dozens of machines and dedicated maintenance teams, small vending machine operators often run a handful of locations themselves, which means every breakdown, theft incident, or product spoilage issue hits harder. That is why finding the right insurance coverage specifically designed for small vending machine operators businesses is not just a safety net—it is a business survival tool. Over the past decade, I have seen too many newcomers skip this step, only to regret it when a machine malfunction caused property damage or a customer got sick from an expired snack. The right policy protects your equipment, your inventory, and your liability exposure, allowing you to focus on growing your route without constant worry.
Why Small Vending Machine Operators Need Specialized Insurance
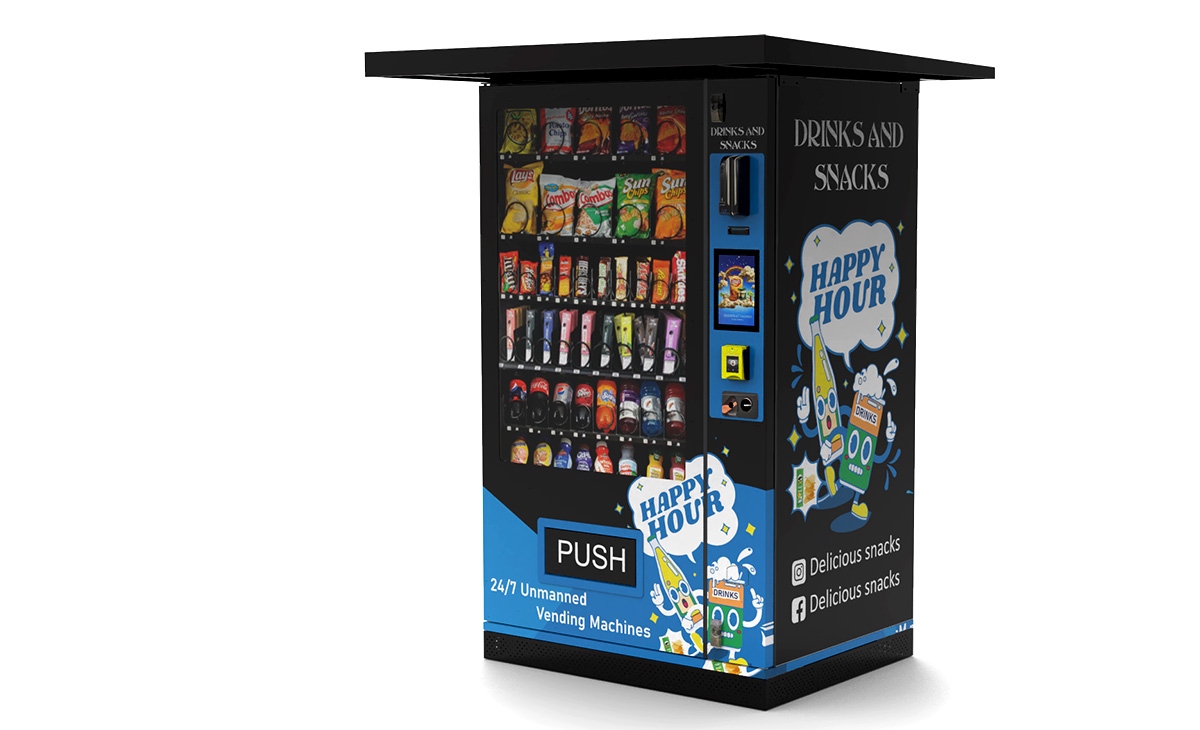
General business insurance often leaves gaps that can be costly for vending machine owners. A standard liability policy might cover a slip-and-fall in your office, but it will not cover a machine tipping over in a busy mall corridor or a power surge frying the payment system. Over the years, I have worked with operators who assumed their landlord’s insurance covered their machines. It does not. You need a policy written specifically for automated retail equipment. This type of coverage typically includes physical damage to the machine, theft of cash and inventory, spoilage of perishable goods, and liability for injuries caused by the machine itself.
Common Coverage Gaps I Have Seen
I once had a client whose machine was placed near a school entrance. A child ran into the glass front, shattering it. The general liability policy the operator had did not cover the machine repair because it was considered “owned property.” That claim came out of pocket. Another operator lost an entire summer’s worth of ice cream inventory when a freezer unit failed overnight. His standard policy excluded spoilage. These are not rare edge cases. According to a 2023 IBISWorld report on vending machine operators in the US, equipment breakdown and inventory loss account for nearly 15% of all operating expenses for small operators. Insurance designed for insurance companies specializing in small vending machine operators businesses closes these gaps by bundling coverage that matches the specific risks of the industry.
What Does a Typical Policy Cover?
When I talk to operators who are shopping for coverage, they often ask what is actually included. Here is a breakdown based on what I have seen work best for small routes of 5 to 20 machines.
Equipment and Machine Coverage
This covers the physical machine itself against fire, vandalism, theft, and accidental damage. If someone rams a cart into your machine in a warehouse, or if a storm damages an outdoor unit, this part of the policy pays for repair or replacement. I always recommend replacement cost coverage rather than actual cash value, because a five-year-old machine might only be worth a fraction of its original cost on paper, but it still generates revenue. Replacement cost ensures you get a comparable new machine, not a depreciated payout.
Inventory and Product Coverage
Perishable goods like sandwiches, salads, and dairy products are high-margin items but also high-risk. If a refrigeration unit fails, you could lose hundreds of dollars in product. Inventory coverage reimburses you for the cost of goods lost due to equipment malfunction, power outage, or spoilage. According to a 2022 study by the National Automatic Merchandising Association (NAMA), spoilage accounts for an average of 4% to 6% of total inventory value per month for small operators. That adds up quickly if you are not insured.
General Liability and Product Liability
If a customer gets sick from a product they bought from your machine, or if someone is injured while using the machine, general liability covers legal fees, medical bills, and settlements. Product liability is especially important for operators selling fresh food. I have seen cases where a sandwich that was past its sell-by date caused food poisoning, and the operator was held responsible even though the supplier packed it. The right policy covers these claims.
Business Interruption and Income Loss
If a machine is damaged and cannot operate while being repaired, business interruption coverage replaces the lost income during that downtime. For a small operator with only a few machines, losing one machine for two weeks could mean a significant drop in monthly revenue. This coverage is often overlooked but can be a lifesaver.
How Much Does Vending Machine Insurance Cost?
The cost of insurance for insurance companies specializing in small vending machine operators businesses varies widely based on the number of machines, their value, the types of products sold, and the locations. Based on my experience and data from industry sources, here is a rough estimate of annual premiums for small operators.
| Number of Machines | Average Annual Premium (USD) | Coverage Type |
|---|---|---|
| 1–5 | $400 – $800 | Basic liability and equipment |
| 6–15 | $800 – $1,500 | Liability, equipment, spoilage |
| 16–30 | $1,500 – $3,000 | Full package including business interruption |
These figures are based on quotes I have seen from providers like The Hartford and Hiscox, as well as data from the Independent Insurance Agents & Brokers of America. Keep in mind that premiums are higher for machines in high-traffic public areas like malls or transit stations compared to private office break rooms. Machines that sell perishable food also cost more to insure than those selling only shelf-stable snacks.
Factors That Influence Your Premium
Not all vending machine businesses are priced the same. Here are the key factors that underwriters consider when quoting your policy.
Location Risk
A machine placed inside a secure office building with limited public access is lower risk than a machine on a street corner or in a park. Vandalism and theft rates vary dramatically by location. I always advise operators to check local crime statistics before placing a machine. According to a 2021 report by Statista, vandalism accounts for 12% of all vending machine insurance claims. Machines in high-crime areas can see premiums 30% to 50% higher than those in low-crime areas.
Machine Type and Value
Older mechanical machines are cheaper to insure because they are less expensive to replace. However, they are also more prone to breakdowns. Modern smart machines with touchscreens, cashless payment systems, and telemetry are more expensive to repair, which can raise your premium. If you are using a machine from a supplier like Zhongda Smart, which offers modern self-service kiosks with advanced payment and monitoring features, make sure your policy covers the full replacement value of the unit, including the electronics.
Product Type
Selling only canned drinks and chips is lower risk than selling fresh sandwiches, salads, or dairy. Perishable items introduce spoilage risk and product liability risk. If you plan to sell fresh food, your insurer will likely require you to have a documented temperature monitoring system and regular maintenance logs for your refrigeration units.
Claims History
If you have filed claims in the past, your premium will be higher. New operators with no claims history often get better rates. I recommend starting with a clean record and maintaining detailed maintenance logs to show insurers that you are a responsible operator.
How to Choose an Insurance Provider
Not all insurance companies understand the vending machine business. I have seen operators buy a general business owner’s policy (BOP) only to find out later that their machines were not covered. You need a provider that specializes in automated retail or at least has a dedicated program for small vending machine operators. Here is what I look for when evaluating an insurer.
Industry Experience
Ask the agent how many vending machine operators they currently insure. If they cannot give you a clear answer, move on. A provider that understands the difference between a snack machine and a frozen food machine will write a better policy. I have had good experiences with providers like The Hartford, which has a dedicated small business division that covers vending operations, and with regional brokers who work with NAMA members.
Coverage Flexibility
Your business will grow and change. You might add machines, move locations, or start selling fresh food. Your policy should allow you to add or remove machines mid-term without heavy penalties. Some insurers offer a “floating” policy that covers a set number of machines regardless of location, which is ideal for operators who frequently move equipment.
Claims Process
I always ask about the claims process before buying a policy. How quickly do they respond? Do they have a dedicated adjuster for equipment claims? Can you file a claim online? A slow claims process can leave you without income for weeks. Look for insurers that offer 24/7 claims reporting and have a reputation for fast payouts.
Common Mistakes Small Operators Make with Insurance
I have been in this industry long enough to see the same mistakes repeated. Here are the most common ones I encounter.
Underinsuring the Machine Value
Many operators insure their machines for what they paid for them, not what it would cost to replace them today. If you bought a machine five years ago for $3,000, that same machine might cost $5,000 to replace now due to inflation and supply chain issues. Always insure for replacement cost, not purchase price.
Skipping Spoilage Coverage
Fresh food vending is growing fast, but spoilage coverage is often an add-on that operators skip to save money. I have seen operators lose $1,000 in product from a single refrigeration failure. That loss could have been covered for an extra $100 per year. Do not skip this coverage if you sell perishables.
Not Reading the Exclusions
Every policy has exclusions. Some exclude damage caused by power surges, others exclude theft of cash if the machine was not properly secured. Read the fine print or ask your agent to explain the exclusions in plain language. I once had a client whose policy excluded “mysterious disappearance” of cash, which meant if the cash count did not match the sales data, the insurer would not pay. That was a costly lesson.
Assuming the Location’s Insurance Covers You
This is the most common misconception. The property owner’s insurance covers the building, not your machine or your liability. If a customer gets injured at your machine, the property owner’s policy will not cover you. You need your own liability coverage. I have seen operators lose their entire business because they relied on someone else’s insurance.
Real Data on Vending Machine Business Risks
To give you a clearer picture, here are some statistics from reputable sources that highlight why insurance is not optional for small vending machine operators.
- According to a 2023 IBISWorld report, the vending machine industry in the US has an average annual failure rate of 8.5% for new operators within the first two years. Equipment damage and liability claims are among the top three reasons for failure.
- A 2022 survey by the National Automatic Merchandising Association (NAMA) found that 22% of vending machine operators experienced at least one liability claim in the previous three years. The average claim amount was $4,200.
- Statista reported in 2021 that vandalism and theft account for 12% of all vending machine claims, with an average cost of $1,800 per incident.
These numbers come from industry bodies and government data sources. They are not theoretical. They represent real risks that small operators face every day.
How to Lower Your Insurance Premium
Insurance is a fixed cost, but there are ways to reduce it without sacrificing coverage. Here are strategies I have used successfully for my own routes and for clients.
Install Security Features
Cameras, alarms, and GPS tracking devices can lower your premium. Many insurers offer discounts for machines equipped with tamper-proof locks and cashless payment systems, which reduce the risk of theft. If you are using a modern machine from Zhongda Smart, it likely already has built-in telemetry and security features. Let your insurer know about these features.
Bundle Policies
If you have multiple insurance needs, such as auto insurance for your route vehicle and liability for your machines, bundling them with the same provider can save 10% to 20% on premiums. Ask your agent about multi-policy discounts.
Maintain a Clean Claims History
This is obvious but worth repeating. Avoid filing small claims if you can afford to pay out of pocket. A single claim can raise your premium for three to five years. I keep a deductible fund of $1,000 per machine to cover minor repairs and losses without involving the insurer.
Regular Maintenance Logs
Insurers like to see that you are actively maintaining your equipment. Keep a log of all service visits, cleaning schedules, and temperature checks for refrigerated units. Some insurers offer a discount of 5% to 10% for operators who can demonstrate regular maintenance.
Frequently Asked Questions About Vending Machine Insurance
Do I really need insurance for a single vending machine?
Yes. Even one machine can cause property damage or injure someone. Without insurance, you are personally liable for any claims. A single lawsuit could cost you tens of thousands of dollars. The annual premium for one machine is usually under $500, which is a small price for peace of mind.
Can I add insurance after I start operating?
You can, but you should not. If something happens before you have coverage, you are on the hook. I always recommend getting insurance before you place your first machine. Most insurers can bind a policy within 24 hours.
Does insurance cover theft of cash from the machine?
It depends on the policy. Many standard policies cover theft of cash up to a certain limit, but they often require proof of forced entry. Some policies exclude “mysterious disappearance,” which means if the cash is missing but there is no sign of break-in, it may not be covered. Read your policy carefully.
What if I operate machines in multiple states?
You need a policy that covers all locations where your machines are placed. Some insurers only cover machines within a single state. If you operate across state lines, look for a provider that offers nationwide coverage. This is especially important if you are placing machines near state borders.
How do I find insurance companies specializing in small vending machine operators businesses?
Start with industry associations like NAMA, which has a list of recommended insurers. You can also ask other operators in local vending machine forums. I have found that regional brokers who work with small businesses often have better rates than national carriers, because they understand the local risk environment.
Is spoilage coverage worth it for a snack-only machine?
If you only sell shelf-stable snacks and drinks, spoilage risk is low. However, if you sell chocolate that can melt in summer or any product with a short shelf life, spoilage coverage is worth considering. For pure snack and soda machines, you can usually skip it.
Can I insure a used or refurbished machine?
Yes, but the coverage amount will be based on the machine’s actual cash value unless you opt for replacement cost coverage. Used machines are cheaper to insure, but if they break down completely, the payout may not be enough to buy a replacement. I recommend replacement cost coverage for any machine that generates consistent revenue.
Final Thoughts from a Long-Time Operator
Insurance is not the most exciting part of running a vending machine business, but it is one of the most important. I have seen operators lose everything because they tried to save a few hundred dollars on a policy that did not cover their real risks. The vending machine industry is full of small margins and big surprises. A broken compressor, a stolen cash box, or a customer injury can happen at any time. The right insurance policy allows you to keep operating even when things go wrong. If you are just starting out, take the time to shop around, ask the right questions, and read the fine print. Your future self will thank you.